

Buy or rent in Norway: what should you compare first?
Share
Save
In brief: Compare buying and renting in Norway by their full costs over the same period, rather than the mortgage payment alone. Include upfront funds, interest, housing costs, tax, a possible move and the loan balance when selling. On 27 October 2026, Norges Bank's policy rate is 4.5%, but that is not your mortgage rate. Checked 27 October 2026.
Which current figures must not be confused?
| Parameter | Figure and qualification | Source |
|---|---|---|
| Policy rate | 4.5%; next rate decision due on 5 November 2026 | Norges Bank: policy rate, checked 27 October 2026 |
| DNB Grønt boliglån example | Nominal rate from 5.49%, effective rate 5.70% in the published example; a product with its own conditions | DNB: loan prices and interest rates, checked 27 October 2026 |
| General maximum loan-to-value rule | Up to 90% of a prudent valuation of the collateral, subject to applicable conditions and exceptions | Finanstilsynet: lending regulation, checked 27 October 2026 |
| Total debt | Normally up to 5 times annual income before tax, including other debts | Finanstilsynet: lending regulation, checked 27 October 2026 |
| Affordability assessment | A rate increase of 3 percentage points, with a minimum tested rate of 7% | Finanstilsynet: lending regulation, checked 27 October 2026 |
| Document duty | Generally 2.5% of market value when registering a property transfer; exemptions exist | Kartverket: document duty, checked 27 October 2026 |
Mortgage approval is not guaranteed. The overall household budget is covered separately in our comparison of living costs in Norway.
Which interest rate should you use in the calculation?
Use your own bank offer with its date, amount, term, rate type and fees. DNB: mortgage interest rates explains the difference between nominal and effective interest (checked 27 October 2026): the former describes interest without additional charges, while the latter includes borrowing costs. Compare offers on the same assumptions.
Norges Bank's policy rate influences the market but does not replace your contract. A public “from” rate for a particular product is not a promise to every buyer either. Clarify the eligibility conditions and the date on which payments change.
How much cash do you need before the purchase?
Separate your down payment, transaction costs and money that will remain available afterwards. The loan-to-value limit in the table does not mean that saving only the difference up to the purchase price is sufficient.
Transferring a borettslag housing-cooperative share does not attract document duty, according to Kartverket: housing cooperatives, checked 27 October 2026, but this does not remove other costs. As DNB: mortgages and shared debt explains (checked 27 October 2026), fellesgjeld is the cooperative's debt, a share of which is attributable to the share owner. Check the total price, your own mortgage, the share of common debt and the items included in felleskostnader, the common charges. Do not add common-debt payments twice if they are already included in those charges.
How does the payment differ from the cost of owning?
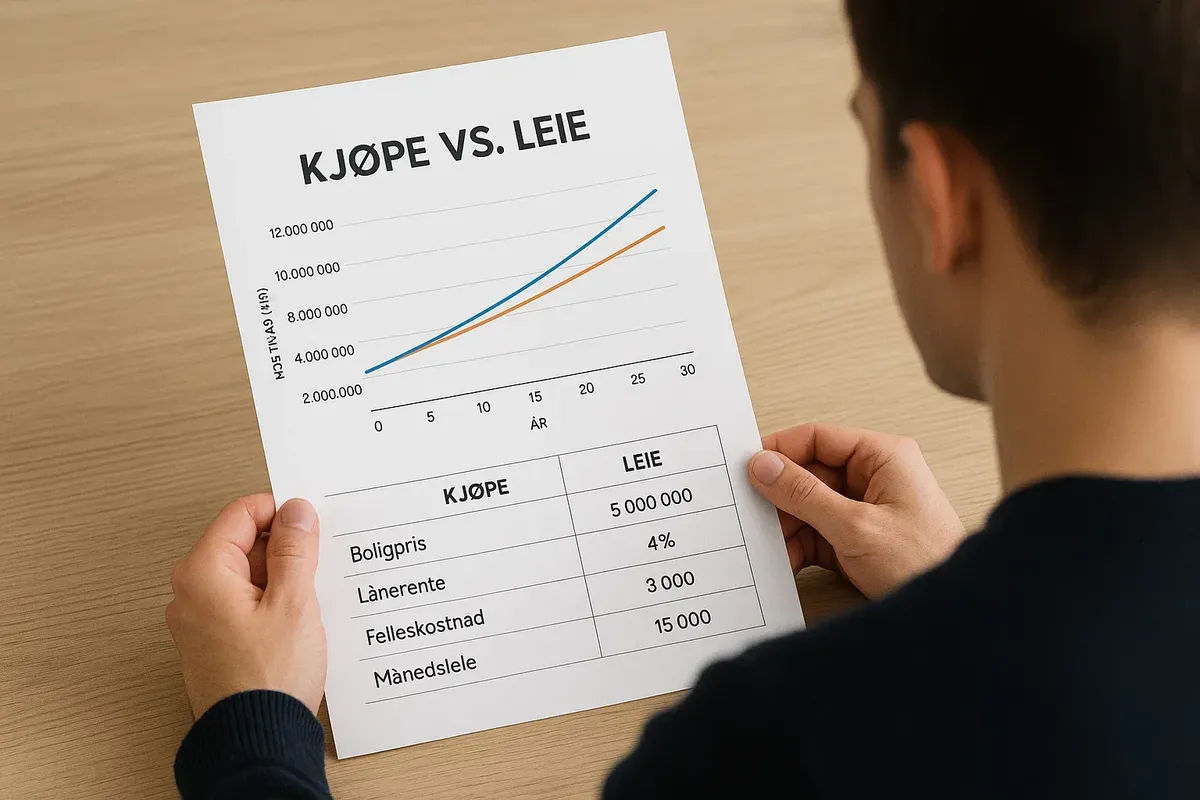
Illustrative calculation, not a bank offer: a 5 000 000 NOK apartment, 1 000 000 NOK of own funds, a 4 000 000 NOK loan, a 25-year term and monthly annuity payments. The example uses the 5.49% nominal rate from a published DNB product for demonstration, not a promised rate for this apartment. Fees and transaction costs are excluded.
| Item | 5.49% | Scenario +3 percentage points: 8.49% |
|---|---|---|
| Monthly payment | 24 540 NOK | 32 182 NOK |
| First month's interest | 18 300 NOK | 28 300 NOK |
| First month's principal repayment | 6 240 NOK | 3 882 NOK |
Formula: payment = P × r / (1 − (1 + r)−n), where P is the loan amount, r is the annual nominal interest rate / 12, and n is the number of months. Figures are rounded to the nearest krone. The higher rate is a scenario, not a forecast or a bank's quoted rate.
Principal repayments reduce the liability, but the money still leaves your account. Add common charges, insurance, running costs and repairs to the monthly budget. For an economic comparison, separate principal repayments from interest and account for the fact that invested capital is tied up. Retain the distinction between interest rates and borrowing costs in your own calculation: DNB: mortgage interest rates, checked 27 October 2026.
How should tax and selling costs be included?
Skatteetaten: allocating loans and interest states a general tax deduction worth 22% of interest expenses (checked 27 October 2026). It relates to interest, not the entire annuity payment. If the loan is joint, check the allocation of debt and interest on the tax card and in the tax return. The tax effect does not automatically reduce the bank payment.
In your sale model, record the sale price, selling costs, remaining personal mortgage and the property's share of common debt separately, along with any tax applicable to your circumstances. Do not assume zero tax by default. A general calculation of income after tax does not replace checking a particular relief.
Important
A positive difference between a future apartment price and the remaining loan is not automatically a profit. Upfront funds, ownership costs and transaction costs must be included on a comparable basis over the entire chosen period.
How do you compare renting without inventing a break-even date?
- Compare equivalent homes and the same period: neighbourhood, floor area, included payments and expected move.
- For renting, use confirmed rent and contractual expenses; note separately the money temporarily tied up in a deposit.
- For buying, list the down payment, transaction, interest, housing costs, repairs and sale.
- Test scenarios with no price growth and a less favourable sale; growth is not guaranteed.
- Assess how much accessible money remains after moving and a payment increase.
Practical searching is covered in our guide to long-term rentals; check payment items against the rental agreement checklist. Deposits and guarantees are compared in a separate guide; they are not treated as non-refundable spending here.
If small changes to assumptions alter the result, the model's conclusion is unstable. Discuss your own figures with the bank and, where needed, a tax specialist. This example helps you prepare questions rather than choosing buying or renting for you. It is not personal financial advice or a bank recommendation.
Frequently asked questions
No. It is the policy rate; your loan rate is determined by the bank contract. Norges Bank: policy rate, checked 27 October 2026.
No. It applies to the stated product and conditions; the bank assesses each applicant individually. DNB: loan prices and interest rates, checked 27 October 2026.
The current general mortgage limit is 90% of the collateral valuation. Transaction costs and affordability are assessed separately; this is not a promise of approval. Finanstilsynet: lending regulation, checked 27 October 2026.
It is a cash outflow you must cover, and at the same time it reduces debt. Do not confuse that payment with the interest cost of borrowing. DNB: mortgage interest rates, checked 27 October 2026.
Kartverket states that transferring such a share does not attract document duty. Other costs and common debt still need checking. Kartverket: housing cooperatives, checked 27 October 2026.
No. The tax effect relates to interest expenses; allocation of a joint loan must be checked separately. Skatteetaten: allocating loans and interest, checked 27 October 2026.
No. Establish the share of common debt, its repayment schedule and what the common charges include. DNB: mortgages and shared debt, checked 27 October 2026.
No. Future interest rates are unknown. Even Norges Bank's forecast is a forecast; your own model should be tested under different conditions. Norges Bank: policy rate, checked 27 October 2026.
Sources
- Norges Bank: policy rate, checked 27 October 2026.
- DNB: mortgage interest rates, checked 27 October 2026.
- DNB: loan prices and interest rates, checked 27 October 2026.
- Finanstilsynet: lending regulation, checked 27 October 2026.
- Kartverket: document duty, checked 27 October 2026.
- Kartverket: housing cooperatives, checked 27 October 2026.
- Skatteetaten: allocating loans and interest, checked 27 October 2026.
- DNB: mortgages and shared debt, checked 27 October 2026.
Author: Ksenia. Updated: 27 October 2026.
Read more
See our overview guide to renting in Norway in 2026: rent, deposits and tenant rights.
Share
Save
Read also
BSU tax deductions in Norway: rules, limits and checks around the new year
Understand BSU relief, 2026 limits, age, home ownership and deposit timing, with checks before withdrawals or planning 2027 saving.
Mortgage interest deductions in Norway: checking your tax card and tax return
Check mortgage interest, annual statements and joint-loan allocation, with 2026 rates and the differences between interest, BSU and PAYE.
How much do spas, saunas and pools cost in Norway in winter?
Compare day prices for spas, saunas and pools in Norway: per-person costs, membership, Christmas opening, inclusions and cancellation conditions.
🌃Nightlife and entertainment in Norway: clubs, bars, festivals and leisure budget (2026 guide)
🍹 How much does nightlife cost in Norway in 2026: prices for clubs (entry from 150 kr), bars, concerts and festivals. A complete guide for travellers and expat…
Which Norwegian traditions and social customs should visitors know?
Explore Norwegian traditions, from 17 May and bunad to dugnad, matpakke and outdoor life. Learn about greetings, home visits, Janteloven and Sámi traditions.
🛡️ Safety, sustainable tourism and accessibility in Norway: what travellers and residents need to know (2026 guide)
🌱 How to travel safely and sustainably in Norway in 2026? A complete guide to safety, sustainable tourism and accessibility: emergency numbers, avalanches, wil…
2 comments
Log in to leave a comment
Hva ville dere gjort i min situasjon — kjøpe nå med rente, eller vente og leie litt lenger? 🤔